A rough patch in your financial past can put a real ceiling on the cards that’ll approve you, and the ones that do often come loaded with restrictions that make it hard to get ahead. The Merrick Bank® Credit Card was built for people in your situation, offering an unsecured line of credit with no deposit required and a structure that rewards you for paying on time.
This CredHelper review pulls apart everything that goes into this card, from the fees and APR to the credit limit mechanics and how it holds up against the competition. It’s the kind of card that tends to fly under the radar, but there’s more to it than the surface suggests. Keep reading and learn what this card can actually do for your credit file.
Read Also: Self Credit Card: Build More Credit Towards Financial Freedom
What is the Merrick Bank® Credit Card and how it works
CredHelper by email
Get our credit guides in your inbox
Plain-English guides that help you make the next move with your credit.
- Reviews of cards for bad or limited credit
- Step-by-step guides to build or rebuild credit
- Help finding loans, benefits and assistance programs
Not every credit card gives people with a rough credit history a fair shot, but that’s precisely the gap the Merrick Bank® Credit Card was built to fill.
This credit building option from Merrick Bank doesn’t require a security deposit to activate, which sets it apart from a lot of cards in this space and keeps the barrier to entry low.
The card comes with a credit limit increase program that kicks in automatically once you hit a certain milestone, giving you more buying power without lifting a finger.
In addition, Merrick Bank reports all on-time payments to the three major credit bureaus in the US, so responsible use gets recorded where it counts for your credit profile.
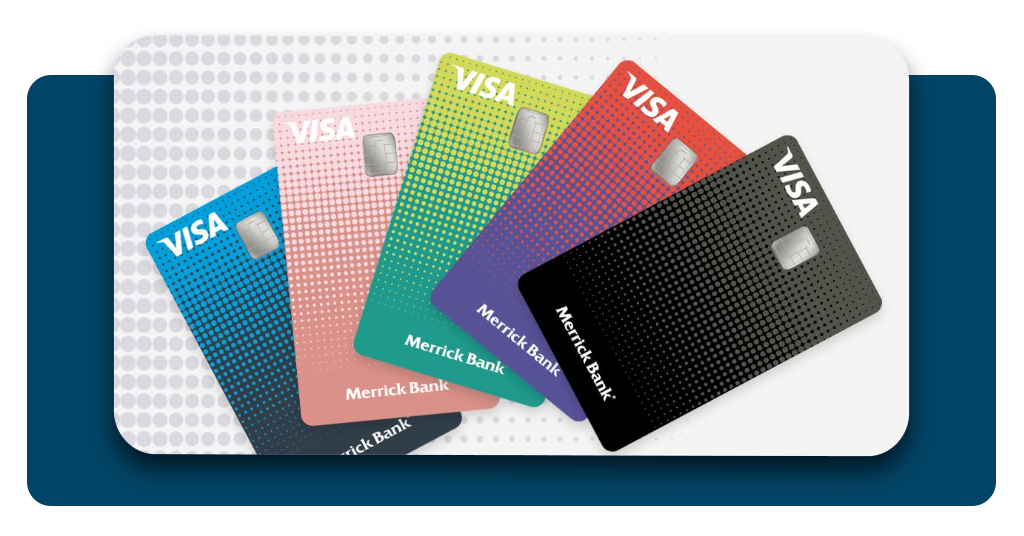
Pros and cons of the Merrick Bank® Credit Card
Every card has a flip side, and the Merrick Bank® Credit Card is no exception. The benefits are real, but so are the costs, and both sides tell an important story.
Some of its perks are genuinely useful for credit builders, but there are a few costs attached that deserve your attention before you commit.
The advantages of having the card
- No security deposit required to open your account;
- Credit limit can grow automatically with on-time payments;
- Free FICO score access directly through the mobile app;
- Reports to all 3 major credit bureaus every month;
- Annual fee can be as low as $ 0,00 depending on your profile.
Potential drawbacks the card has
- APR reaches up to 34.45%, which adds up fast if you carry a balance;
- Annual fee can reach up to $72 in the first year;
- Cash advance fee is $ 10,00 or 4%, whichever hits harder;
- No rewards program of any kind attached to this card;
- Card is only available through a pre-approved mail offer invitation.
Does Merrick Bank help rebuild your credit score?
Credit rebuilding is one of those things that sounds simple until you’re in the middle of it. The Merrick Bank® Credit Card addresses that struggle with a structure that works.
Two features do most of the heavy lifting here. One is about visibility, the other is about growth, and together they cover the core of what makes this card functional for a bruised credit file.
Merrick Bank’s three bureau reporting explained
Not all credit cards report to every bureau. Some skip one or two, which leaves gaps in your credit file that can hurt your score even if you’re doing everything right.
This card sends your payment activity to all three every month. That means your payments build a consistent record across the board, giving your score the best foundation to grow from.
The “Double Your Line” credit limit program
Carrying the Merrick Bank® Credit Card also opens the door to one of its more compelling features, a credit limit increase that happens without you having to even ask for.
Hit your minimum payment on time for the first 7 months and your limit doubles automatically. A higher limit with the same spending habits translates directly into a better credit utilization ratio.
Read Also: Low credit? boost your score with this credit score simulator
Fees, APR, and credit limits explained clearly
Fees aren’t the most exciting topic, but they’re the numbers that’ll hit your bank account if you’re not paying attention. This card has a cost structure that varies from person to person.
The credit limit side tells a different story. It starts modest, but there’s a mechanic attached to this card that can change your financial picture over time.
Annual fee structure breakdown
The Merrick Bank® Credit Card charges an annual fee ranging from $ 0,00 to $ 72,00 in the first year, with the exact amount tied to your specific offer and credit profile.
After year one, that fee switches to a monthly charge of $ 0,00 to $ 6,00. The maximum annual cost stays at $ 72,00, but how it’s billed changes once your first year wraps up.
APR ranges and what they mean
Purchase APR runs from 29.45% to 34.45%, and cash advance APR sits even higher at 34.45% to 35.00%. Those figures hit hard if you’re not clearing your balance every billing cycle.
This card wasn’t designed for carrying debt from month to month. Treating it as a pay-in-full tool is the only approach that keeps those rates from turning into a real financial burden.
Starting credit limits and increase potential
Your initial limit falls between $ 300,00 and $ 1,350, which gives you enough room to establish a spending pattern without the temptation of a high available balance pulling you off track.
Consistent on-time payments open the door to an automatic limit increase, and the Merrick Bank® Credit Card handles that process without a hard inquiry or any action on your part.
Who qualifies for the Merrick Bank® Credit Card
Not every applicant will qualify for this card, and that’s actually by design. Merrick Bank targets a specific group of people, and the eligibility criteria reflect that pretty clearly.
If you’ve got a limited credit history or a score that’s taken some hits, this card was put together with your profile in mind. Here’s what the qualification side of things looks like.
Credit score requirements for this card
This card sits in the fair to poor credit range, generally accessible to people with scores below 670. It’s one of the few unsecured options that doesn’t shut the door on a damaged credit file.
However, a low score alone doesn’t guarantee approval. Merrick Bank also weighs your income, existing debt load, and overall credit behavior when deciding what offer, if any, to extend to you.
Merrick Bank’s invitation process
Applying for a Merrick Bank® Credit Card isn’t as simple as heading to a website and filling out a form. The bank sends pre-approved offers by mail to people who fit their lending criteria.
If you haven’t received a mailer, there’s no direct application path available to you at this point. Your best move is to keep your credit profile active and in good shape until an offer lands.
Step-by-step: how your limit increases automatically
One of the more practical things about this card is that your credit limit doesn’t just sit still. There’s a built-in process that moves it upward without you having to do anything about it.
That automatic increase isn’t luck though. It follows a specific timeline and a set of conditions that are laid out from day one, so you always know where you stand.
Timeline and requirements for credit limit increase
The window for your limit increase is the first 7 months your account is open. During that period, your payment behavior is what determines whether the increase kicks in or not.
Miss a single minimum payment in those 7 months and the opportunity resets. Staying on track the entire time is the only thing separating you from a limit that’s twice what you started with.
What triggers your automatic limit increase
Paying your Merrick Bank® Credit Card statement on time signals to the bank that you’re a low-risk borrower, and the automatic increase is essentially their response to that pattern.
It’s not tied to your income, your spending volume, or how long you’ve had credit. The trigger is behavioral, which levels the playing field for people who are rebuilding from a rough stretch.
How to apply for a Merrick Bank® Credit Card step-by-step
The application process for this card doesn’t follow the usual path you’d expect from a credit card. There’s no public form to fill out, and you can’t just decide one day to sign up.
Merrick Bank controls who gets access to this card by working through a mail-based system. If you’ve received an offer, the process from there is pretty simple to follow.
Step 1: finding and accepting your mail offer
Your offer arrives as a physical mailer with a reservation number printed on it. That number is your entry point, so don’t toss it before checking what the offer includes.
Head to Merrick Bank’s website and enter your reservation number to pull up your specific terms. Your credit limit, APR, and annual fee will all be listed there for you to review.
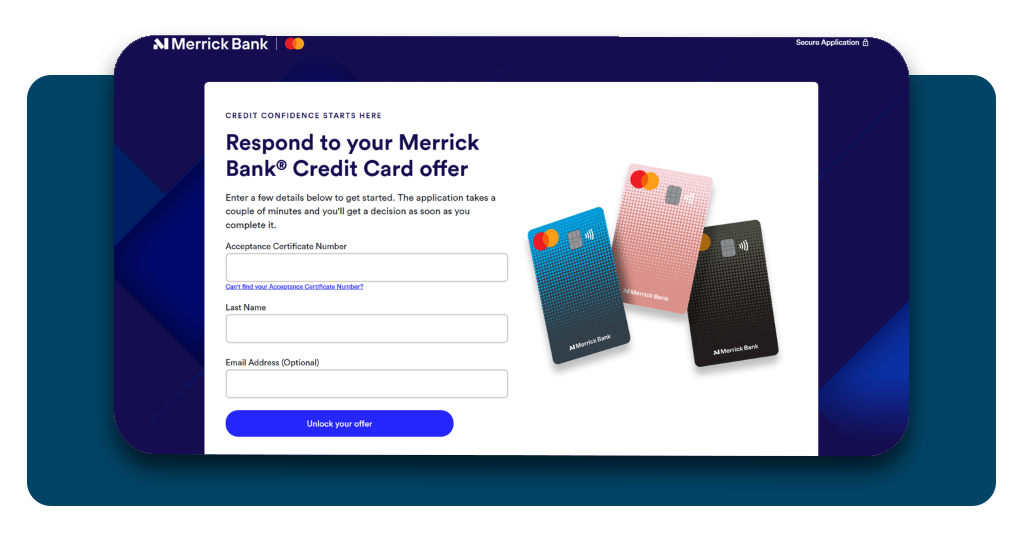
Step 2: submitting your application and next steps
Once you accept your offer, filling out a Merrick Bank® Credit Card application takes just a few minutes. You’ll provide personal and financial details, and the bank takes it from there.
Approval decisions don’t drag on for long, and if you’re approved, your card ships out shortly after. Once it arrives, setting up autopay from the start puts you in the best possible position.
Read Also: Chime Credit Card Visa: Benefits, Eligibility and How to Apply
Tips to maximize your limit and improve your credit
Getting the most out of this card has less to do with how much you spend and more to do with how consistently you manage it. Small habits add into real credit score movement over time.
There are a couple of specific areas where your behavior directly affects both your limit and your credit profile. Nail these two things and the card does a lot of the work for you.
Best habits for consistent on-time payments
Setting up autopay for at least the minimum amount due removes the human error factor. You won’t have to track due dates manually or risk a late payment derailing your progress.
If autopay isn’t your preference, calendar reminders set a few days before the due date give you enough buffer to transfer funds and confirm the payment went through without any scrambling.
Using your card responsibly to build credit
Keeping your balance well below your credit limit is one of the most direct levers you have on your score. Staying under 30% of your available credit is the threshold.
That and the Merrick Bank® Credit Card‘s bureau reporting means every low-balance, on-time month gets recorded. That kind of activity is what shifts your credit from shaky to solid over time.
Merrick Bank® Credit Card vs other bad credit credit cards
Picking a credit card for bad credit goes beyond just getting approved. The real question is which option gives you the most room to grow without draining your wallet in the process.
Some competitors offer things this card doesn’t, and vice versa. Laying them out next to each other gives you a clearer picture of where this card fits in the landscape.
Cards that compete with Merrick Bank’s offer
The Platinum Secured Credit Card from Capital One is one of the more common alternatives in this space. It has no annual fee and also targets fair credit borrowers.
The Destiny® Mastercard® and the Merrick Bank® Credit Card both sit in similar territory in terms of accessibility, but Destiny tends to carry higher fees with fewer built-in incentives.
Where Merrick Bank stands out and falls short
The automatic limit increase program is truly rare in this credit tier. Most cards in this range make you request an increase manually or wait for the issuer to decide on their own schedule.
Where it loses ground is on the cost side. The APR and the annual fee put it at a disadvantage next to competitors, particularly for anyone who’s close to qualifying for a mid-tier card.
A practical tool for real credit progress
This card won’t turn your credit around overnight, but it gives you the right conditions to make real progress if you stick to the basics.
The automatic limit increase and bureau reporting are what set the Merrick Bank® Credit Card apart in this space. This CredHelper review laid out everything you need to make that call.
Explore other CredHelper reviews for a fuller picture of what the credit card market has to offer. There’s a whole range of options covered, and one of them could be exactly the fit you need.